Off-plan payment plans in Dubai: 60/40, 1% a month and post-handover
How a Dubai payment plan works: 60/40, 75/25, 1% a month and post-handover plans explained, with real instalment figures, handover funding and the risks.
8 min read · Updated 13 October 2026 · Independent guide, checked against official sources
A Dubai payment plan lets you pay for an off-plan home in stages while it is built, instead of all at once. The numbers in the name tell you the split: on a 60/40 plan you pay 60% of the price before completion and 40% at handover. Developers do not normally charge interest on these instalments, and every payment goes into a project escrow account regulated by the Dubai Land Department (DLD).
The main formats in 2026 are 60/40, 70/30 and 75/25 plans, "1% a month" plans and, less often, post-handover plans that run on after you receive the keys. Most start with a booking payment of around 20%, and the 4% DLD fee is due near the start as well.
Below, each plan type is worked through with real figures from projects on this site, followed by how to fund the handover payment and what happens if you miss an instalment.
How a Dubai payment plan works
Every off-plan plan has three parts:
- Booking. A down payment when you reserve, commonly 10% to 20%. All of the "from" plans listed below start at 20%. The 4% DLD registration fee is usually collected at the same time, because the developer must register your contract in the DLD's interim register (Oqood).
- Construction instalments. Paid monthly, quarterly or at construction milestones until the building is finished.
- Handover. The balance, paid when the building is complete and before you receive the keys and title deed.
Instalments are either time-linked (fixed dates) or construction-linked (tied to a percentage of completion). With construction-linked plans, the DLD suggests checking the confirmed completion percentage, published on its website, before you pay a milestone.
Your sale and purchase agreement (SPA) fixes the schedule. Read it before paying the booking amount, because it is binding once signed.
Dubai payment plan types compared
| Plan | Before handover | At handover | Example on this site |
|---|---|---|---|
| 60/40 | 60% | 40% | DAMAC District, Valencia in DAMAC Lagoons |
| 70/30 (1% monthly) | 70% | 30% | Chelsea Residences |
| 75/25 | 75% | 25% | DAMAC Islands 2, DAMAC Islands |
| Post-handover | Part | Part at handover, the rest in instalments after the keys | None listed at present |
The 60/40 plan
The classic Dubai structure. You pay 60% during construction and 40% at handover, which gives you time to arrange a mortgage or build up cash for the final payment.
DAMAC District in DAMAC Hills, from AED 808,000 (about €200,000), combines a 60/40 split with 1% monthly instalments:
| Stage | Share | At the "from" price | In euros |
|---|---|---|---|
| Booking | 20% | AED 161,600 | about €39,900 |
| 1% a month for 40 months | 40% | AED 8,080 a month | about €2,000 a month |
| Handover, due Q3 2029 | 40% | AED 323,200 | about €79,800 |
Add the 4% DLD fee of AED 32,320 (about €8,000) near the start. Valencia in DAMAC Lagoons District, from AED 1,520,000, follows the same 20/40/40 shape with instalments to 2029.
The 1% a month plan
"1% a month" is a marketing name for a plan in which, after the booking payment, you pay 1% of the price every month for a set number of months. It is easy to budget, because the instalment never changes, and it suits buyers paying from monthly income.
Chelsea Residences in Dubai Maritime City, from AED 2,457,000 (about €607,000), uses a 20/50/30 version:
| Stage | Share | At the "from" price | In euros |
|---|---|---|---|
| Booking | 20% | AED 491,400 | about €121,300 |
| 1% a month for 50 months | 50% | AED 24,570 a month | about €6,070 a month |
| Handover, due Q4 2029 | 30% | AED 737,100 | about €182,000 |
Lagoon Views, from AED 1,625,000, is also sold on a 1% monthly plan with handover due in Q2 2027. Because handover is close, ask for the exact balance still due on the current release.
The catch with any 1% plan is commitment. The instalment is due every month for years, whatever happens to your income, your currency or the market.
The 75/25 plan
A 75/25 plan front-loads the payments, leaving only a quarter for handover. It suits cash buyers who want a smaller final bill.
DAMAC Islands 2, villas and townhouses from AED 2,994,000 (about €739,000), runs 20% at booking, 55% during construction and 25% on handover:
| Stage | Share | At the "from" price | In euros |
|---|---|---|---|
| Booking | 20% | AED 598,800 | about €147,900 |
| Monthly instalments to 2030 | 55% | AED 1,646,700 in total | about €406,600 in total |
| Handover, due Q2 2030 (4 BR) | 25% | AED 748,500 | about €184,800 |
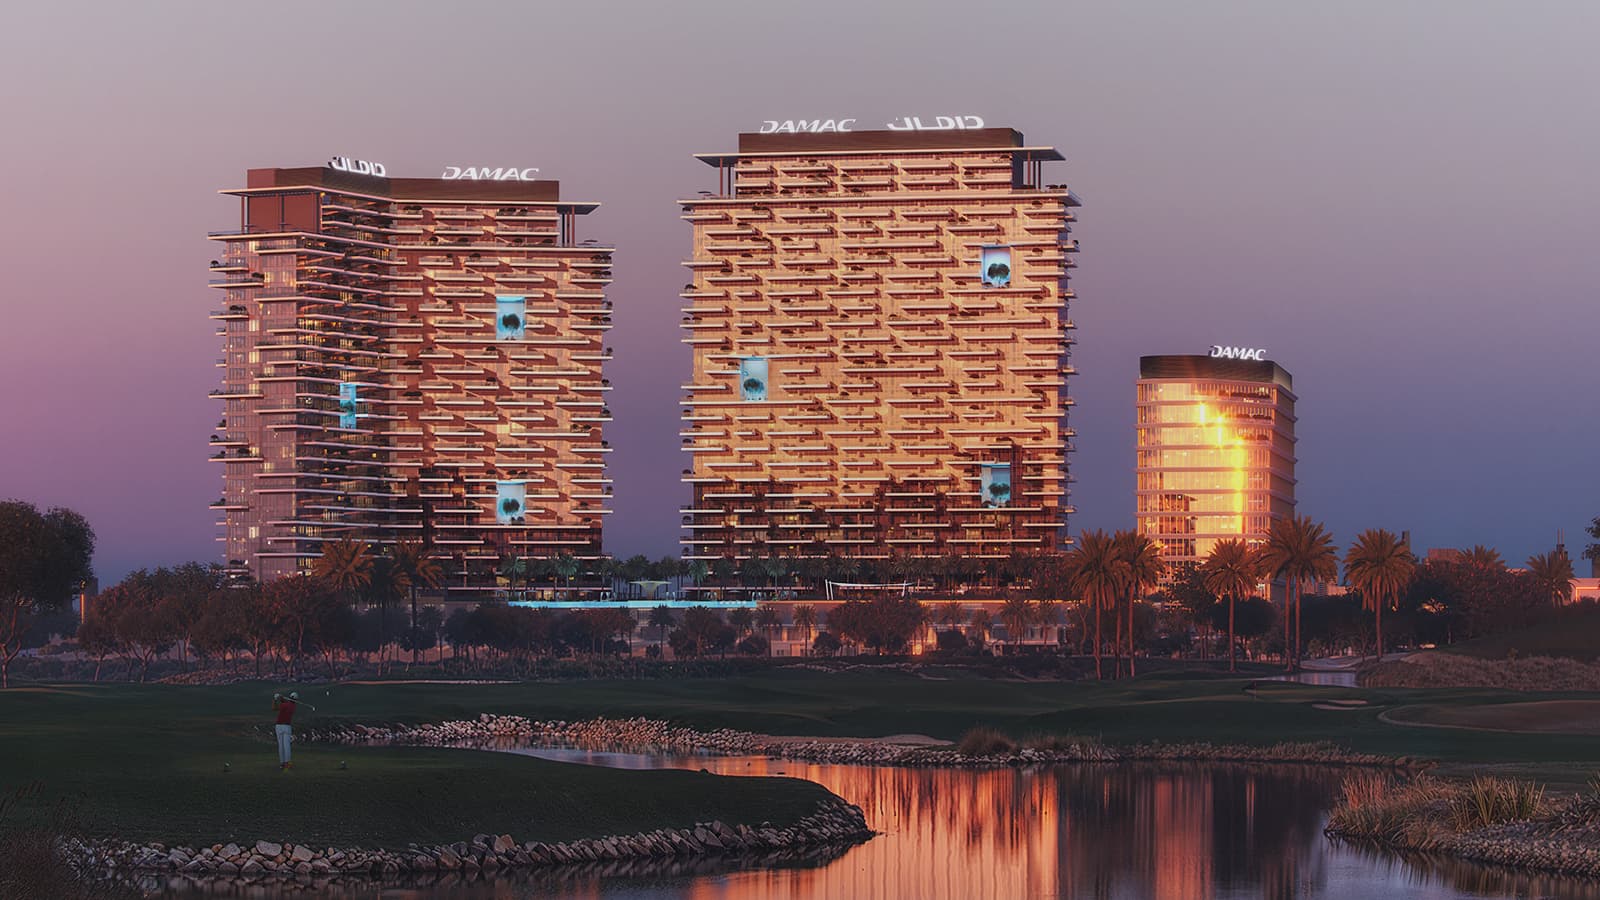
DAMAC Hills
DAMAC District
From AED 808,000 ≈ €200k
Q3 2029
Studio – 2 BR · 60/40 with 1% monthly instalments
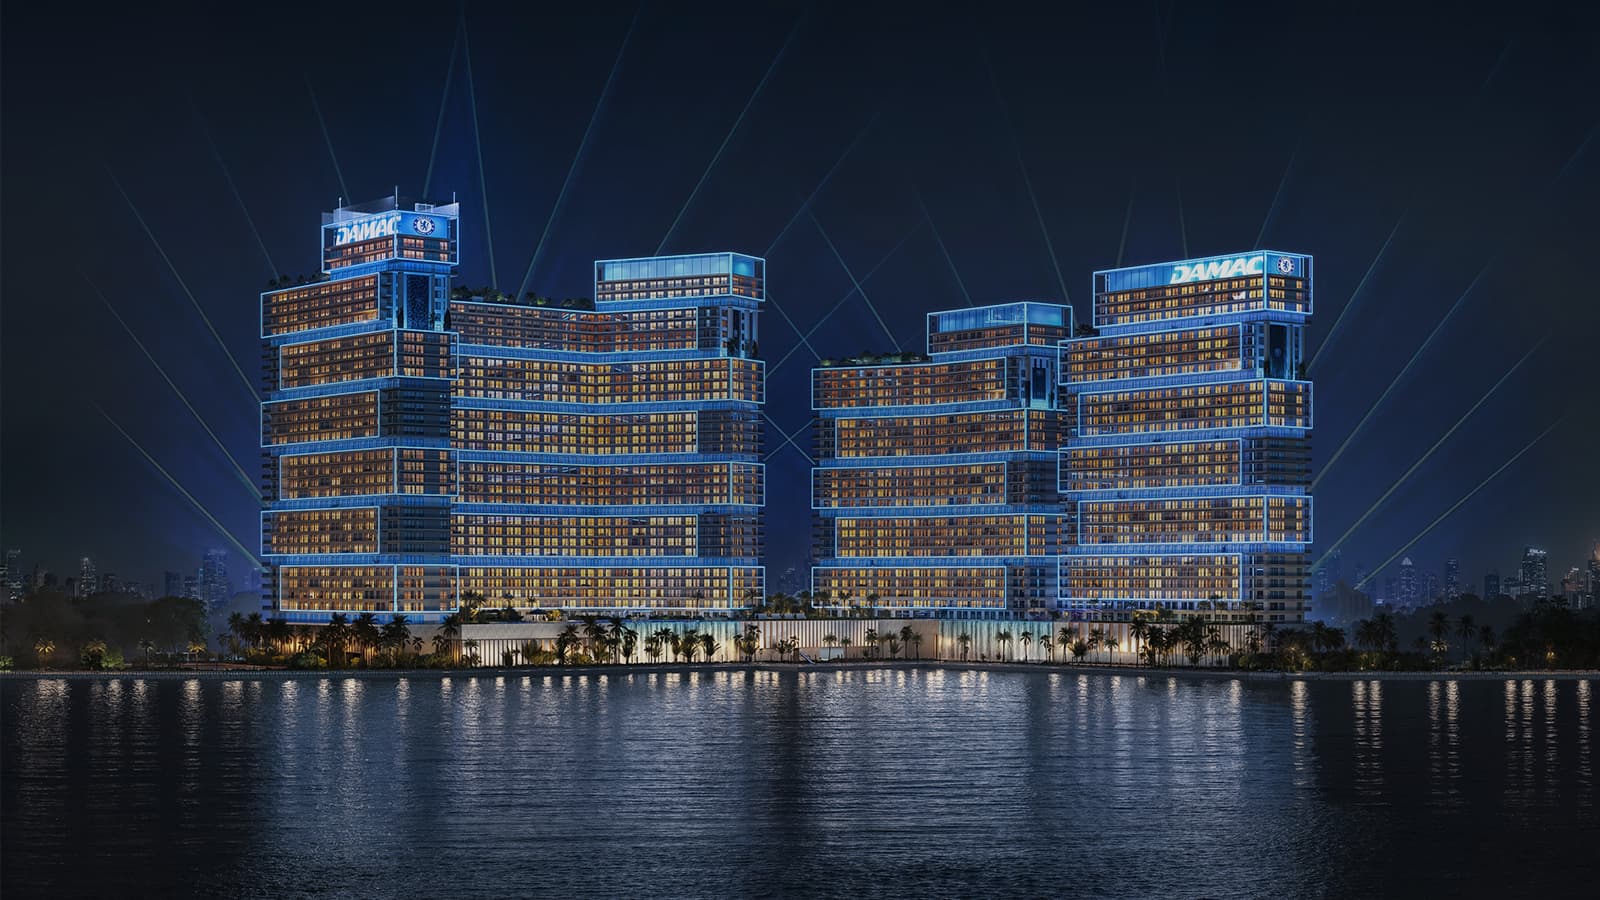
Dubai Maritime City
Chelsea Residences
From AED 2,457,000 ≈ €607k
Q4 2029
1–3 BR · 1% monthly plan
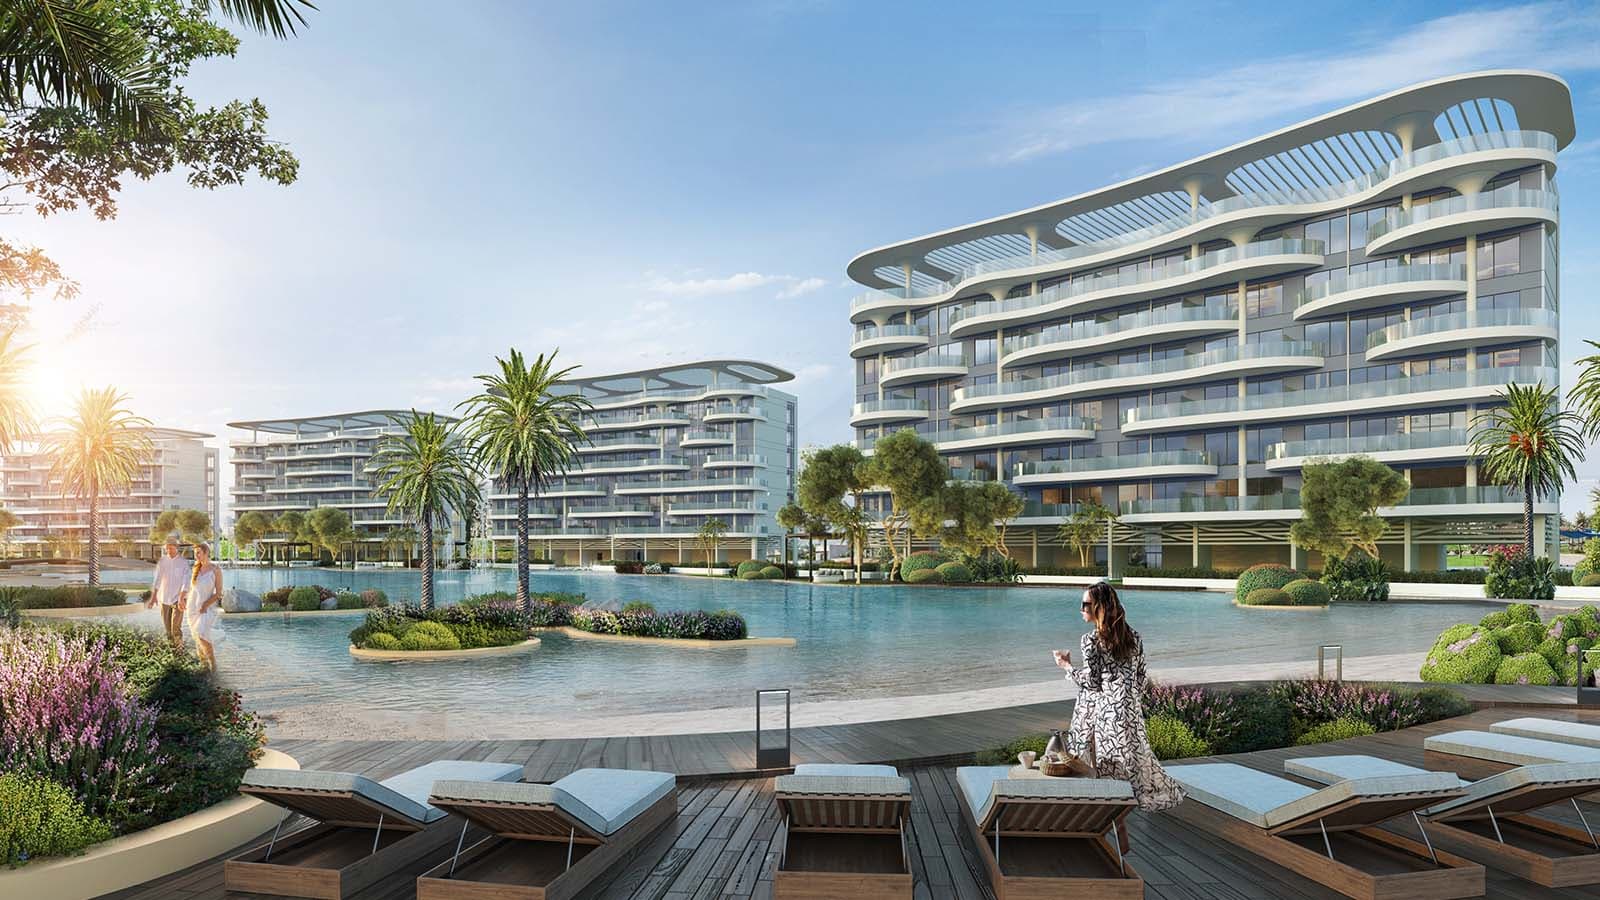
DAMAC Lagoons
Lagoon Views
From AED 1,625,000 ≈ €401k
Q2 2027
1–2 BR · 1% monthly plan
Dubailand
DAMAC Islands 2
From AED 2,994,000 ≈ €739k
Q2 2030
4–5 BR · 75/25
Post-handover plans
On a post-handover plan, part of the price is paid in instalments for a period after you receive the keys, often a few years. In theory, rent from the finished home helps cover the instalments.
None of the projects currently listed on this site uses one. If you are offered one, compare the price with the same unit on a standard plan. Developers carry the credit risk, so the price can be higher, and you are paying the developer rather than a bank while you also carry service charges and any letting costs.
What a payment plan really costs
Developer plans are usually interest-free in name, but not free in effect.
- The price may include the financing. Ask whether there is a discount for paying more up front or in cash. If there is, that discount is the real cost of the plan.
- The DLD fee comes first. 4% of the full price is normally due at registration, not spread across the plan. See our breakdown of Dubai property buying costs.
- Currency moves. If you pay from euros or pounds over four or five years, each instalment costs a different amount in your home currency.
- Service charges start at handover, at the same time as your biggest payment.
Funding the handover payment
The handover payment is the largest single cheque, and the one buyers most often underestimate. There are three ways to fund it.
Cash. Simplest, if you have saved it during construction.
A mortgage at completion. Once the building is finished, a UAE bank can lend against it as a ready property. The handover share on most plans is 25% to 40%, comfortably inside the 50% to 60% that non-resident buyers can usually borrow. Our guide to a non-resident mortgage in Dubai covers the bank criteria, and the calculator shows the monthly cost.
Calculator
Dubai mortgage calculator
Monthly repayments in dirhams and euros. Non-residents can usually borrow 50 to 60% of the value; most banks lend at handover, not during an off-plan build.
Monthly payment
AED 6,326
≈ €1,562 a month
Loan
AED 1,000,000
50% of the price
Total interest
AED 518,359
over 20 years
Illustration only, not an offer. Rates are usually a fixed period then linked to EIBOR; banks also charge arrangement, valuation and DLD mortgage registration fees (see the buying costs calculator).
Selling before handover. Some buyers sell their contract to a new buyer before completion. Many developers require a minimum share of the price to be paid before they allow this, and charge a fee. It depends on finding a buyer at the right price, so do not rely on it as your only plan.
What happens if you miss a payment
Off-plan defaults follow a process set out in Article 11 of Dubai's interim register law, as amended by Law No. 19 of 2017. The developer must notify the DLD, which gives you 30 days to pay or settle. After that, depending on how far construction has progressed, the developer can cancel and keep up to 25% or up to 40% of the contract value, or, once the building is more than 80% complete, keep the contract and pursue the balance or ask the DLD to auction the unit.
Losing up to 40% of the price is a serious risk. Only commit to a schedule you can meet from money you already have or income you are confident of. Our guide to buying off-plan in Dubai covers these protections in full.
Which payment plan suits you
- Investors watching cash flow: a 60/40 or 1% plan keeps more money in your hands until handover, but leaves a bigger final payment.
- Cash buyers: a 75/25 plan, or a discount for paying more up front, reduces the handover bill.
- Buyers relying on rent to pay: a post-handover plan, if offered, but check the price premium carefully.
- Anyone borrowing: make sure the handover share fits what a bank will lend you, before you book.
To compare plans across current launches, see our round-up of new off-plan projects in Dubai, or ask for a shortlist through the enquiry form.
Frequently asked questions
What is a 60/40 payment plan in Dubai?+
You pay 60% of the price during construction, including the booking payment, and the remaining 40% when the building is handed over. The 4% DLD fee is paid separately, usually near the start.
What does a 1% payment plan mean in Dubai?+
After the booking payment, you pay 1% of the price every month for a fixed number of months: 40 at DAMAC District and 50 at Chelsea Residences, for example. The rest is paid at handover, or after it on a post-handover version.
Do Dubai developers charge interest on payment plans?+
Usually not in name. The instalments add up to the list price. The cost can be built into that price, so ask whether paying in cash or up front earns a discount.
Can I sell an off-plan property before I finish paying?+
Often yes, but many developers require a minimum share of the price to be paid first and charge a transfer fee. The resale is registered with the DLD, and the new buyer takes over the remaining instalments.
What happens if I cannot pay an off-plan instalment in Dubai?+
The developer must go through the DLD, which gives you 30 days to pay or settle. If you do not, the developer can cancel and keep up to 25% or 40% of the contract value depending on construction progress, refunding the rest.
General information as of 13 October 2026, not legal, tax or financial advice. Rules and prices change; a licensed broker confirms the current position before you commit.
Keep reading
All guidesBuying guide · 9 min
Buying off-plan in Dubai: escrow, Oqood and how your money is protected
Buying off-plan in Dubai explained: how escrow and Oqood registration protect your money, the steps to buy, the 4% DLD fee and the risks the law leaves to you.
Read the guideBuying guide · 8 min
Getting a mortgage in Dubai as a non-resident
Can you get a mortgage in Dubai as a non-resident? Yes, from some UAE banks. Loan-to-value limits, off-plan and buy-to-let rules, documents, costs and examples.
Read the guideBuying guide · 9 min
Dubai property buying costs: the DLD fee and every charge on top
Dubai Land Department fees explained: the 4% DLD fee, Oqood, trustee and title deed fees, commission, mortgage costs and service charges, with examples.
Read the guideGet a shortlist
Five questions. One honest shortlist.
Tell us what you are after and a licensed partner sends three to five projects that fit, with real payment schedules in euros.
Step 1 of 5